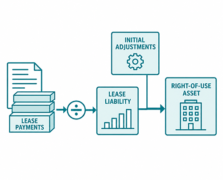
How to Calculate a Right-of-Use Asset and Lease Liability
Explore the calculation of lease liabilities and right-of-use assets under IFRS 16 and FRS 102, from present value and discount rates to depreciation.
Explore the calculation of lease liabilities and right-of-use assets under IFRS 16 and FRS 102, from present value and discount rates to depreciation.
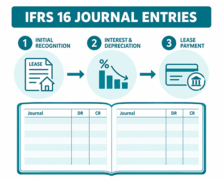
A detailed guide to IFRS 16 journal entries, covering lease recognition, interest, liability repayments, depreciation and the transition to FRS 102 in 2026.
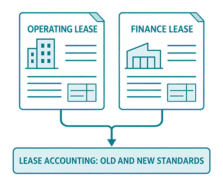
Examine the distinction between operating and finance leases, how IFRS 16 and FRS 102 changed lessee accounting, and why ASC 842 retains it.

Understand how IFRS 16, revised FRS 102 and ASC 842 approach lease accounting, including recognition, measurement, exemptions and reporting implications.

Read how St George’s NHSFT combined FMIS cloud-hosted software to track assets and ensure IFRS 16 compliance in this NHS Fixed Asset and Lease Accounting Case Study

