FMIS Software
  • Home
  • Solutions
    • Fixed Asset Management Systems
      • Capital Projects
      • Enterprise Asset Management
      • Fixed Asset Management Software
    • Asset Tracking
      • Barcode Tracking
      • FMIS Mobile Asset Manager
    • Purchase to Pay
      • Purchase Order Processing
      • Sales Order Processing
    • Stock and Inventory
      • Kitting and Assembly
      • Material Requirements Planning (MRP)
      • Production Control
    • Equipment Maintenance
      • Field Service Management
    • Lease Accounting
      • Order Management
  • Market Sectors
    • Public Sector
      • Local Government and Councils
      • Central Government
      • Government Agencies and Public Bodies
      • Emergency Services
    • Commercial and Retail
    • Education
    • Health
    • Manufacturing
    • Non-Profit
    • Oil, Gas and Energy
  • Partners
    • Deltek
    • Find a partner
    • Become a Partner
  • Resources
    • Trust Centre
      • Certifications & Assurance
      • Data Protection & Privacy
      • Cloud Security & Infrastructure
    • News and articles
    • Case studies
    • Fixed asset management guide
  • About us
  • Contact
    • Request a demo
    • Pricing
    • Product information
    • Customer Support
    • Careers
    • Training Feedback
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
You are here: Home1 / Articles2 / How to Calculate a Right-of-Use Asset and Lease Liability

How to Calculate a Right-of-Use Asset and Lease Liability

When a lease goes on the balance sheet, two figures have to be calculated: the lease liability and the right-of-use asset. This guide explains what each is, how to work them out, which payments to include, and shows a full worked example with numbers. The same basic on-balance-sheet model applies under IFRS 16 and, from 2026, under FRS 102, although measurement and application differences remain.

Written by: John de Robeck • Published: September 3, 2026 • Updated: September 29, 2026

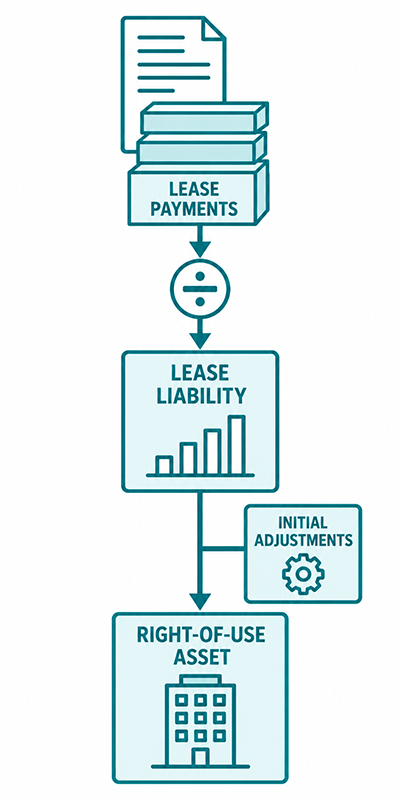
Flow Diagram depicting the process to calculate right of use asset and lease liability

What is a right-of-use asset?

A right-of-use asset is the asset a lessee recognises to represent its right to use a leased item over the lease term. It is not the leased item itself, which the lessor still owns, but the value of the right to use it. It is measured from the lease liability plus certain additional costs, then depreciated.

Think of it as capitalising the deal: instead of showing rent as it is paid, you record the value of what you have the right to use, and then write that value down over the time you use it. It behaves much like an owned fixed asset once it is on the books, which is why many organisations track right-of-use assets in the same register as their owned assets.

What is a lease liability?

A lease liability is the present value of the future lease payments the lessee is committed to make over the lease term. It is the debt side of the lease. As payments are made, part reduces the liability and part is charged as interest, so the liability unwinds to nil by the end of the lease.

The liability is calculated first, because the right-of-use asset is built on top of it. Present value is used because a promise to pay 10,000 pounds a year for five years is not worth 50,000 pounds today; future payments are discounted back to what they are worth now.

How to calculate the lease liability

Calculate the lease liability in three steps: determine the lease term, list the lease payments due over that term, and discount them to present value using the appropriate rate. The discount rate is the interest rate implicit in the lease if it can be readily determined, otherwise the lessee’s incremental borrowing rate.

The lease term is the non-cancellable period plus any optional extension the lessee is reasonably certain to take. The discount rate matters, because a higher rate produces a smaller liability. Under IFRS 16 the default is the incremental borrowing rate where the implicit rate is not readily available; FRS 102 allows an obtainable borrowing rate as a more practical alternative.

Which lease payments to include

Include the payments the lessee is committed to: fixed payments, less any lease incentives receivable; variable payments that depend on an index or a rate; amounts expected to be payable under residual value guarantees; and the exercise price of a purchase option if the lessee is reasonably certain to exercise it.

  • Fixed payments, and in-substance fixed payments, less any incentives due from the lessor.
  • Variable payments linked to an index or rate, measured using the rate at commencement.
  • Amounts expected to be payable under residual value guarantees.
  • The purchase option price, if exercise is reasonably certain.
  • Termination penalties, if the lease term reflects the lessee ending the lease early.

Purely variable payments that depend on use or sales are excluded from the liability and expensed as incurred, because they are not committed at the start.

How to calculate the right-of-use asset

The right-of-use asset starts from the lease liability, then adds any payments made at or before commencement, initial direct costs, and estimated dismantling or restoration costs, and deducts any lease incentives received. In the simplest case, with none of those extras, the asset equals the liability.

So the liability is the foundation and the asset is the liability adjusted for the costs of getting the lease in place. Once recognised, the asset is depreciated on a straight-line basis, usually over the shorter of the lease term and the asset’s useful life.

A worked example

Take a five-year lease with payments of 10,000 pounds a year in arrears and a discount rate of 5 percent. The present value of those five payments is about 43,295 pounds. With no other costs, the lease liability and the right-of-use asset are both 43,295 pounds at the start.

In year one, interest is 5 percent of 43,295, which is about 2,165 pounds. The 10,000 pound payment therefore reduces the liability by 7,835 pounds, leaving about 35,460 pounds. Depreciation of the asset is 43,295 divided by five, about 8,659 pounds a year. So the first-year charge to profit and loss is roughly 2,165 of interest plus 8,659 of depreciation, about 10,824 pounds, compared with a flat 10,000 pound rent under the old operating-lease approach. That higher early charge is the front-loading effect. The bookkeeping for this example is set out in our guide to IFRS 16 journal entries.

Subsequent measurement

After commencement, the two figures move independently. The lease liability grows by interest and shrinks by payments each period. The right-of-use asset is depreciated over the lease term. They rarely match after year one, and both reach nil by the end of the lease in a simple case.

If the lease changes, for example a rent review or a change in term, the liability is remeasured and the asset is adjusted. Remeasurements are one of the areas where spreadsheets struggle and where dedicated lease accounting software earns its place.

The FRS 102 simplifications

From 2026, FRS 102 uses the same broad right-of-use model but with practical simplifications. Lessees may use an obtainable borrowing rate instead of the harder-to-calculate incremental borrowing rate, and fewer lease modifications require the use of a revised discount rate.

The outcome is very similar to IFRS 16, but the method is a little easier to run, which suits the smaller finance teams that apply FRS 102. The detail is in our FRS 102 2026 guide, and the choice of standard is covered in our comparison of IFRS 16 and FRS 102.
Frequently Asked Questions

What discount rate should you use?

Use the interest rate implicit in the lease if it can be readily determined. If not, use the lessee’s incremental borrowing rate under IFRS 16, or, from 2026, an obtainable borrowing rate under FRS 102, which may be available from existing lenders.

Is the right-of-use asset the same as the leased asset?

No. The leased asset remains owned by the lessor. The right-of-use asset is the lessee’s right to use it over the lease term, recognised on the lessee’s balance sheet and depreciated over that term.

Do you have to remeasure the figures?

Yes, when the lease changes in certain ways, such as a revised term or an index-linked payment change. The liability is remeasured and the right-of-use asset adjusted. Under revised FRS 102, fewer lease modifications require the use of a revised discount rate.

What is included in the cost of a right-of-use asset?

The right-of-use asset starts at the amount of the lease liability, plus any payments made at or before the commencement date, initial direct costs, and an estimate of dismantling or restoration costs. Any lease incentives received are deducted. It is then depreciated over the lease term.

What is the incremental borrowing rate?

The incremental borrowing rate is the rate a lessee would pay to borrow, over a similar term and with similar security, the funds needed to obtain an asset of similar value. IFRS 16 uses it to discount the lease payments when the interest rate implicit in the lease cannot be readily determined.

About the author

John de Robeck leads new business and partnerships at FMIS, working with organisations to understand asset and equipment maintenance requirements, software fit and related compliance considerations.

Read full bio

Share this content
  • Facebook Facebook Share on Facebook
  • X-twitter X-twitter Share on X
  • Whatsapp Whatsapp Share on WhatsApp
  • Linkedin Linkedin Share on LinkedIn
  • Mail Mail Share by Mail

Flow diagram showing the decision-making process between the different lease accounting standards for IFRS 16 and FRS 102

IFRS 16 vs FRS 102: Which Lease Accounting Standard Applies to You?

Compare IFRS 16 and FRS 102 lease accounting, including their scope, pre-2026 differences, the 2026 changes and the practical differences that remain.
https://www.fmis.co.uk/wp-content/uploads/2026/09/ifrs-16-vs-frs-102-lease-accounting-office-featured.webp 500 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-04 16:15:472026-09-29 16:33:37IFRS 16 vs FRS 102: Which Lease Accounting Standard Applies to You?
Simple flow diagrams showing the application of ASC 842 Lease Accounting for US GAAP Reporters

ASC 842 Lease Accounting: A Guide for US GAAP Reporters

Understand ASC 842 lease accounting, including classification, measurement, exemptions and the key differences from IFRS 16 and revised FRS 102.
https://www.fmis.co.uk/wp-content/uploads/2026/09/asc-842-lease-accounting-us-gaap-featured-image.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-04 16:07:062026-09-29 16:34:53ASC 842 Lease Accounting: A Guide for US GAAP Reporters
Flow Diagram depicting the process to calculate right of use asset and lease liability

How to Calculate a Right-of-Use Asset and Lease Liability

Explore the calculation of lease liabilities and right-of-use assets under IFRS 16 and FRS 102, from present value and discount rates to depreciation.
https://www.fmis.co.uk/wp-content/uploads/2026/09/accounting-office-banner-calculating-lease-liability.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-03 09:33:012026-09-29 16:30:34How to Calculate a Right-of-Use Asset and Lease Liability
IFRS 16 Journal entries flow diagram

IFRS 16 Journal Entries: A Step-by-Step Worked Example

A detailed guide to IFRS 16 journal entries, covering lease recognition, interest, liability repayments, depreciation and the transition to FRS 102 in 2026.
https://www.fmis.co.uk/wp-content/uploads/2026/09/diverse-accountants-ifrs16-lease-management.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-03 09:27:172026-09-29 16:32:21IFRS 16 Journal Entries: A Step-by-Step Worked Example
Support Icon
Can we help?
Book a demo View products Contact support
Or call: +44 (0) 1227 773003
Mon–Fri, 9:00–17:00 (BST/GMT)

Explore More

  • What is new in FMIS Fixed Assets version 12.47
  • What is new in FMIS Lease Accounting version 12.47
  • AccountMate Fixed Asset Integration with FMIS
  • Asset Depreciation Methods Explained for UK Businesses
  • How to Conduct a Fixed Asset Audit: Step by Step

SOLUTIONS

  • Fixed Asset Management Systems
  • Asset Tracking
  • Purchase to Pay
  • Order Management
  • Equipment Maintenance
  • Lease Accounting
  • Stock and Inventory
  • View all solutions

Home › Articles › Lease Accounting: IFRS 16, FRS 102 and ASC 842 Guide › How to Calculate a Right-of-Use Asset and Lease Liability

Market Sectors

  • Commercial and Retail
  • Education
  • Local and Central Government
  • NHS and Health
  • Manufacturing
  • Non-profit
  • Oil, Gas and Energy

FOLLOW US

FMIS Twitter FMIS Linkedin

CONTACT US

FMIS Ltd
167b John Wilson Business Park
Whitstable
Kent
CT5 3RA
United Kingdom

Phone:+44 (0) 1227 773003
Fax:+44 (0) 1227 773005
Sales:sales@fmis.co.uk
Support:support@fmis.co.uk

Copyright © 2024 - All rights reserved www.fmis.co.uk
  • Privacy Policy
  • Cookie Policy
Scroll to top