FMIS Software
  • Home
  • Solutions
    • Fixed Asset Management Systems
      • Capital Projects
      • Enterprise Asset Management
      • Fixed Asset Management Software
    • Asset Tracking
      • Barcode Tracking
      • FMIS Mobile Asset Manager
    • Purchase to Pay
      • Purchase Order Processing
      • Sales Order Processing
    • Stock and Inventory
      • Kitting and Assembly
      • Material Requirements Planning (MRP)
      • Production Control
    • Equipment Maintenance
      • Field Service Management
    • Lease Accounting
      • Order Management
  • Market Sectors
    • Public Sector
      • Local Government and Councils
      • Central Government
      • Government Agencies and Public Bodies
      • Emergency Services
    • Commercial and Retail
    • Education
    • Health
    • Manufacturing
    • Non-Profit
    • Oil, Gas and Energy
  • Partners
    • Deltek
    • Find a partner
    • Become a Partner
  • Resources
    • Trust Centre
      • Certifications & Assurance
      • Data Protection & Privacy
      • Cloud Security & Infrastructure
    • News and articles
    • Case studies
    • Fixed asset management guide
  • About us
  • Contact
    • Request a demo
    • Pricing
    • Product information
    • Customer Support
    • Careers
    • Training Feedback
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
You are here: Home1 / Articles2 / ASC 842 Lease Accounting: A Guide for US GAAP Reporters

ASC 842 Lease Accounting: A Guide for US GAAP Reporters

ASC 842 is the US GAAP lease accounting standard. It brought most leases onto the balance sheet, as IFRS 16 did internationally, but it kept the operating and finance classification for lessees because the two produce different expense patterns. This guide explains the scope, the classification criteria, the measurement, and how ASC 842 differs from IFRS 16 and revised FRS 102.

Written by: John de Robeck • Published: September 4, 2026 • Updated: September 29, 2026

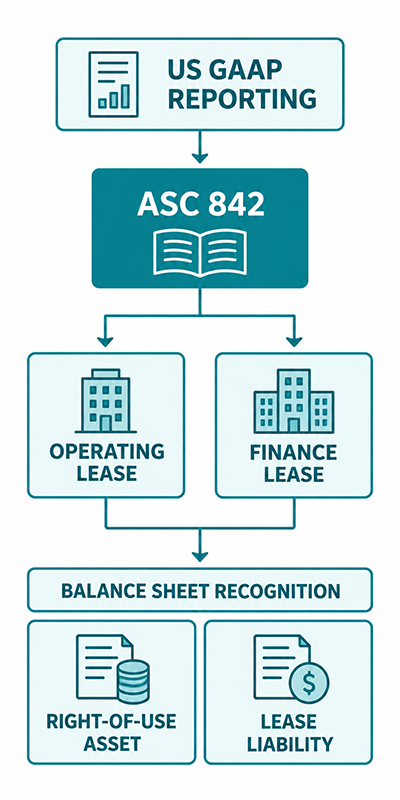
Simple flow diagrams showing the application of ASC 842 Lease Accounting for US GAAP Reporters

What is ASC 842?

ASC 842 is the FASB standard governing how entities reporting under US GAAP account for leases. It replaced ASC 840 and requires a lessee to recognise a right-of-use asset and a lease liability for most leases, rather than leaving operating leases off the balance sheet with only the commitments disclosed.

Under ASC 840, an operating lease produced a rent expense and a note. The commitments were visible only to a reader who went looking for them. ASC 842 was written to close that gap, for the same reason the IASB wrote IFRS 16: a business that leases its premises and a business that borrows to buy them carry similar obligations and should not look entirely different in the accounts.

When did ASC 842 take effect?

ASC 842 took effect for public business entities for fiscal years beginning after 15 December 2018, which meant calendar-year adopters applied it from 1 January 2019. For all other entities it took effect for fiscal years beginning after 15 December 2021.

That staggered adoption is why private US companies were still working through first-time application several years after listed companies had finished, and why transition questions on ASC 842 surfaced later than they did for IFRS 16.

Who does ASC 842 apply to?

ASC 842 applies to entities preparing financial statements under US GAAP. For a UK organisation this usually arises in one of two ways: a UK subsidiary reporting into a US parent that consolidates under US GAAP, or a group with US operations that must prepare figures on both bases.

Dual reporting is where the differences below stop being academic. The same lease can require an IFRS 16 measurement for the statutory accounts and an ASC 842 classification for the group submission.

How ASC 842 classifies leases

A lessee classifies each lease as finance or operating at commencement. The lease is a finance lease if any one of five criteria is met, and an operating lease if none is met.

  1.     Ownership of the underlying asset transfers to the lessee by the end of the lease term.
  2.     The lease contains a purchase option the lessee is reasonably certain to exercise.
  3.     The lease term is for a major part of the remaining economic life of the underlying asset.
  4.     The present value of the lease payments and any residual value guarantee amounts to substantially all of the fair value of the underlying asset.
  5.     The underlying asset is so specialised that it is expected to have no alternative use to the lessor at the end of the lease term.

The third and fourth criteria are not expressed as bright lines. PwC’s Viewpoint guidance notes that applying thresholds of 75 per cent of remaining economic life and 90 per cent of fair value is one reasonable approach to those tests, which is where the familiar percentages from the old standard survive in practice.

Operating and finance leases: what actually differs

Both classifications put a right-of-use asset and a lease liability on the balance sheet. The difference is entirely in what happens next.

  Operating lease Finance lease
Initial recognition Right-of-use asset and lease liability Right-of-use asset and lease liability
Income statement A single straight-line lease cost across the term Amortisation of the right-of-use asset plus interest on the liability
Expense profile Level Front-loaded
Where it is presented Within operating expenses Amortisation and interest presented separately
Cash flow statement Payments within operating activities Interest and principal presented separately
Effect on EBITDA Reduced, because the lease cost is an operating expense Protected, because amortisation and interest sit below the line

 That last row is the reason classification is examined closely on US GAAP engagements. Two companies with the same leases and the same balance sheet can report a materially different operating profit and a materially different EBITDA, purely because of how the leases were classified at commencement.

Measuring the lease liability and right-of-use asset

The mechanics will be familiar to anyone who has applied IFRS 16. The lease liability is the present value of the lease payments over the lease term, discounted at the rate implicit in the lease where that is readily determinable, and otherwise at the lessee’s incremental borrowing rate. The right-of-use asset starts from the liability and is adjusted for prepayments, initial direct costs and incentives.

Our guide to calculating a right-of-use asset and lease liability works through that arithmetic with a full example. The measurement is the same in outline; what differs under ASC 842 is how the asset is written down afterwards, because an operating lease produces a single straight-line cost rather than separate amortisation and interest.

What is exempt under ASC 842?

ASC 842 offers a short-term lease policy election. A lessee may choose, by class of underlying asset, not to recognise leases with a term of 12 months or less that do not include a purchase option the lessee is reasonably certain to exercise. Payments on those leases are recognised on a straight-line basis instead.

There is no low-value exemption equivalent to the one in IFRS 16. An organisation with a large population of small leases, laptops, printers, small equipment, therefore has less relief available under ASC 842 than the same organisation would have under IFRS 16, and the population that has to be measured is larger.

ASC 842 compared with IFRS 16 and revised FRS 102

  ASC 842 IFRS 16 FRS 102 from 2026
Lessee model Dual. Operating or finance Single Single
Most leases on balance sheet Yes Yes Yes
Short-term relief Policy election by asset class Exemption available Exemption available
Low-value relief None Available Available, with examples of what is not low value
Operating lease expense Single straight-line lease cost Not applicable. Depreciation and interest Not applicable. Depreciation and interest
Discount rate Rate implicit in the lease, otherwise incremental borrowing rate Rate implicit in the lease, otherwise incremental borrowing rate Obtainable borrowing rate permitted
Lessor accounting Classification retained Largely unchanged Largely unchanged

 For a UK reader the practical summary is this. If you already understand IFRS 16, you understand most of ASC 842. What you have to add back is the classification test, the two expense patterns that follow from it, and the absence of a low-value exemption.

Managing ASC 842 alongside IFRS 16 or FRS 102

Dual reporting is the hardest part of ASC 842 for organisations outside the United States. The same lease population has to be measured under one framework for the statutory accounts and classified under another for the group submission, with two sets of postings and two sets of disclosures drawn from one set of contracts.

This is where spreadsheets break down first. Maintaining one model is manageable. Maintaining two, kept in step through every modification and remeasurement, is where errors enter and where audit questions concentrate.

FMIS lease accounting software is built for lessee financial accounting under IFRS 16, ASC 842 and revised FRS 102. It maintains the lease population, calculates lease liabilities and right-of-use assets, handles modifications and remeasurements, produces reporting, posts to the general ledger, and links right-of-use assets with FMIS Fixed Assets.

SCOPE

FMIS Lease Accounting supports lessee financial accounting. It does not provide lessor accounting, and it is not a broad operational lease administration system.

Frequently Asked Questions

What is ASC 842 in simple terms?

ASC 842 is the US GAAP rule that puts leases on the balance sheet. A lessee recognises a right-of-use asset for what it has the right to use and a lease liability for what it owes, then classifies the lease as operating or finance, which determines how the cost is recognised over the term.

Is ASC 842 the same as IFRS 16?

No. Both bring most lessee leases onto the balance sheet, but IFRS 16 uses a single lessee model while ASC 842 keeps the operating and finance classification. ASC 842 also has no low-value exemption, and the two standards differ on income statement and cash flow presentation.

Are operating leases on the balance sheet under ASC 842?

Yes. Both operating and finance leases are recognised on the balance sheet as a right-of-use asset and a lease liability. What differs is the expense: an operating lease produces a single straight-line lease cost, while a finance lease produces amortisation and interest.

When did ASC 842 become effective?

For public business entities, fiscal years beginning after 15 December 2018. For all other entities, fiscal years beginning after 15 December 2021. Calendar-year public companies therefore adopted it on 1 January 2019.

Does ASC 842 have a low-value exemption?

No. ASC 842 provides a short-term lease policy election for leases of 12 months or less, applied by class of underlying asset, but there is no low-value exemption equivalent to the one available under IFRS 16.

Does a UK company need to apply ASC 842?

Not for UK statutory reporting, which uses IFRS 16 or FRS 102. ASC 842 becomes relevant where a UK entity reports into a US parent that consolidates under US GAAP, or where a group prepares figures on both bases.

Sources

  •       PwC Viewpoint, Leases guide, section 3.3 Lease classification criteria.
  •       KPMG Financial Reporting View, FASB leases standard amendments, effective dates.
  •       RSM, Leases: overview of ASC 842.

About the author

John de Robeck leads new business and partnerships at FMIS, working with organisations to understand asset and equipment maintenance requirements, software fit and related compliance considerations.

Read full bio

Share this content
  • Facebook Facebook Share on Facebook
  • X-twitter X-twitter Share on X
  • Whatsapp Whatsapp Share on WhatsApp
  • Linkedin Linkedin Share on LinkedIn
  • Mail Mail Share by Mail
Flow diagram showing the decision-making process between the different lease accounting standards for IFRS 16 and FRS 102

IFRS 16 vs FRS 102: Which Lease Accounting Standard Applies to You?

Compare IFRS 16 and FRS 102 lease accounting, including their scope, pre-2026 differences, the 2026 changes and the practical differences that remain.
https://www.fmis.co.uk/wp-content/uploads/2026/09/ifrs-16-vs-frs-102-lease-accounting-office-featured.webp 500 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-04 16:15:472026-09-29 16:33:37IFRS 16 vs FRS 102: Which Lease Accounting Standard Applies to You?
Simple flow diagrams showing the application of ASC 842 Lease Accounting for US GAAP Reporters

ASC 842 Lease Accounting: A Guide for US GAAP Reporters

Understand ASC 842 lease accounting, including classification, measurement, exemptions and the key differences from IFRS 16 and revised FRS 102.
https://www.fmis.co.uk/wp-content/uploads/2026/09/asc-842-lease-accounting-us-gaap-featured-image.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-04 16:07:062026-09-29 16:34:53ASC 842 Lease Accounting: A Guide for US GAAP Reporters
Flow Diagram depicting the process to calculate right of use asset and lease liability

How to Calculate a Right-of-Use Asset and Lease Liability

Explore the calculation of lease liabilities and right-of-use assets under IFRS 16 and FRS 102, from present value and discount rates to depreciation.
https://www.fmis.co.uk/wp-content/uploads/2026/09/accounting-office-banner-calculating-lease-liability.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-03 09:33:012026-09-29 16:30:34How to Calculate a Right-of-Use Asset and Lease Liability
IFRS 16 Journal entries flow diagram

IFRS 16 Journal Entries: A Step-by-Step Worked Example

A detailed guide to IFRS 16 journal entries, covering lease recognition, interest, liability repayments, depreciation and the transition to FRS 102 in 2026.
https://www.fmis.co.uk/wp-content/uploads/2026/09/diverse-accountants-ifrs16-lease-management.webp 450 500 John de Robeck https://www.fmis.co.uk/wp-content/uploads/2026/04/FMISNavyTeal-1-150x80-1.webp John de Robeck2026-09-03 09:27:172026-09-29 16:32:21IFRS 16 Journal Entries: A Step-by-Step Worked Example
Support Icon
Can we help?
Book a demo View products Contact support
Or call: +44 (0) 1227 773003
Mon–Fri, 9:00–17:00 (BST/GMT)

Explore More

  • What is new in FMIS Fixed Assets version 12.47
  • What is new in FMIS Lease Accounting version 12.47
  • AccountMate Fixed Asset Integration with FMIS
  • Asset Depreciation Methods Explained for UK Businesses
  • How to Conduct a Fixed Asset Audit: Step by Step

SOLUTIONS

  • Fixed Asset Management Systems
  • Asset Tracking
  • Purchase to Pay
  • Order Management
  • Equipment Maintenance
  • Lease Accounting
  • Stock and Inventory
  • View all solutions

Home › Articles › Lease Accounting: IFRS 16, FRS 102 and ASC 842 Guide › ASC 842 Lease Accounting

Market Sectors

  • Commercial and Retail
  • Education
  • Local and Central Government
  • NHS and Health
  • Manufacturing
  • Non-profit
  • Oil, Gas and Energy

FOLLOW US

FMIS Twitter FMIS Linkedin

CONTACT US

FMIS Ltd
167b John Wilson Business Park
Whitstable
Kent
CT5 3RA
United Kingdom

Phone:+44 (0) 1227 773003
Fax:+44 (0) 1227 773005
Sales:sales@fmis.co.uk
Support:support@fmis.co.uk

Copyright © 2024 - All rights reserved www.fmis.co.uk
  • Privacy Policy
  • Cookie Policy
Scroll to top