What journal entries does IFRS 16 require?
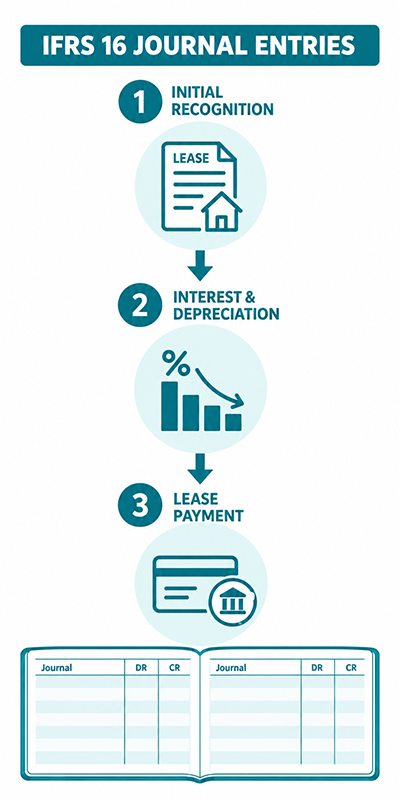
IFRS 16 requires three kinds of entry for a lessee: one at commencement to recognise the right-of-use asset and lease liability, entries each period to record the lease payment as part interest and part repayment, and a depreciation entry each period to write down the asset. The pattern repeats until the lease ends.
The key idea is that a single rent payment is split. Under the old operating-lease approach the whole payment was an expense. Under IFRS 16 the payment reduces a liability and only the interest portion is an expense, while the asset is depreciated separately. That is why two expense lines, interest and depreciation, replace the single rent line.
Step 1: Recognition at commencement
At the start of the lease, recognise the right-of-use asset and the lease liability at the present value of the lease payments. Using the worked example of a five-year lease at 10,000 pounds a year and 5 percent, both are about 43,295 pounds.
- Dr Right-of-use asset 43,295
- Cr Lease liability 43,295
If there were initial direct costs or a payment made before commencement, they would be added to the right-of-use asset with a credit to cash. In this simple example there are none, so the asset and liability start equal. The measurement behind these figures is explained in our guide to calculating a right-of-use asset.
Step 2: The lease payment each period
Each period, split the lease payment into interest and repayment of the liability. Interest is the discount rate applied to the opening liability; the rest reduces the liability. In year one, interest is about 2,165 pounds and the repayment is about 7,835 pounds, totalling the 10,000 pound payment.
- Dr Interest expense 2,165
- Dr Lease liability 7,835
- Cr Cash 10,000
The interest portion falls each year as the liability shrinks, so the repayment portion grows. By the final year almost all of the payment is repayment and very little is interest, and the liability reaches nil.
Step 3: Depreciation each period
Each period, depreciate the right-of-use asset, usually straight-line over the lease term. In the example, 43,295 pounds over five years is about 8,659 pounds a year. This is a separate entry from the lease payment and is what replaces part of the old rent charge.
- Dr Depreciation expense 8,659
- Cr Accumulated depreciation 8,659
So the total charge to profit and loss in year one is about 2,165 of interest plus 8,659 of depreciation, roughly 10,824 pounds. That is higher than the 10,000 pound rent that the old operating-lease treatment would have shown, which is the front-loading effect that IFRS 16 introduced.
Step 4: The end of the lease
In this simplified example, by the end of the lease term the lease liability has been repaid to nil and the right-of-use asset has been fully depreciated to nil. No additional closing entry is required in the example. In practice, end-of-lease accounting depends on the contract, any purchase or extension options, modifications and the condition in which the asset is returned.
In this simplified example, the total interest and depreciation recognised over the lease equals the total cash paid. In practice, initial direct costs, incentives, restoration obligations, variable payments, modifications and other adjustments can cause total recognised expense to differ from the contractual cash payments shown in a basic example.
The same basic posting pattern under FRS 102 from 2026
From accounting periods beginning on or after 1 January 2026, FRS 102 lessees use the same broad on-balance-sheet model and therefore the same basic posting pattern: recognise the asset and liability, split each payment into interest and repayment, and depreciate the asset. Measurement, transition and application differences can still affect the amounts posted.
So a finance team moving from the old FRS 102 rules will see the bookkeeping change from a single rent expense to this three-part pattern. The full transition, including the one-off adjustment to opening retained earnings, is covered in our FRS 102 2026 guide.
How the lease unwinds over the term
Across the lease term the liability falls as payments are made, the interest charge shrinks each year as the balance reduces, and the right-of-use asset depreciates on a straight line. By the final payment the liability reaches nil and the asset is fully depreciated, so both leave the balance sheet together.
Using the same example, the opening liability of 43,295 reduces to 35,460 after year one, then continues to fall as more of each 10,000 payment goes to principal and less to interest. The right-of-use asset falls by 8,659 a year regardless. Setting the two schedules side by side shows why the total charge is higher in the early years and lower later, even though the cash paid is the same each year.