What is a right-of-use asset?
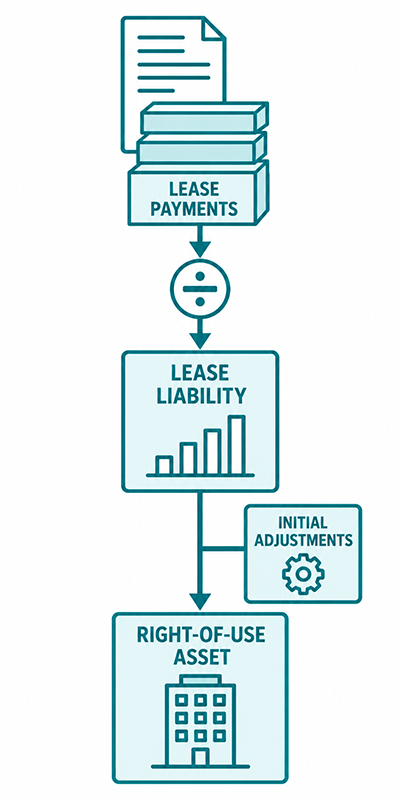
A right-of-use asset is the asset a lessee recognises to represent its right to use a leased item over the lease term. It is not the leased item itself, which the lessor still owns, but the value of the right to use it. It is measured from the lease liability plus certain additional costs, then depreciated.
Think of it as capitalising the deal: instead of showing rent as it is paid, you record the value of what you have the right to use, and then write that value down over the time you use it. It behaves much like an owned fixed asset once it is on the books, which is why many organisations track right-of-use assets in the same register as their owned assets.
What is a lease liability?
A lease liability is the present value of the future lease payments the lessee is committed to make over the lease term. It is the debt side of the lease. As payments are made, part reduces the liability and part is charged as interest, so the liability unwinds to nil by the end of the lease.
The liability is calculated first, because the right-of-use asset is built on top of it. Present value is used because a promise to pay 10,000 pounds a year for five years is not worth 50,000 pounds today; future payments are discounted back to what they are worth now.
How to calculate the lease liability
Calculate the lease liability in three steps: determine the lease term, list the lease payments due over that term, and discount them to present value using the appropriate rate. The discount rate is the interest rate implicit in the lease if it can be readily determined, otherwise the lessee’s incremental borrowing rate.
The lease term is the non-cancellable period plus any optional extension the lessee is reasonably certain to take. The discount rate matters, because a higher rate produces a smaller liability. Under IFRS 16 the default is the incremental borrowing rate where the implicit rate is not readily available; FRS 102 allows an obtainable borrowing rate as a more practical alternative.
Which lease payments to include
Include the payments the lessee is committed to: fixed payments, less any lease incentives receivable; variable payments that depend on an index or a rate; amounts expected to be payable under residual value guarantees; and the exercise price of a purchase option if the lessee is reasonably certain to exercise it.
- Fixed payments, and in-substance fixed payments, less any incentives due from the lessor.
- Variable payments linked to an index or rate, measured using the rate at commencement.
- Amounts expected to be payable under residual value guarantees.
- The purchase option price, if exercise is reasonably certain.
- Termination penalties, if the lease term reflects the lessee ending the lease early.
Purely variable payments that depend on use or sales are excluded from the liability and expensed as incurred, because they are not committed at the start.
How to calculate the right-of-use asset
The right-of-use asset starts from the lease liability, then adds any payments made at or before commencement, initial direct costs, and estimated dismantling or restoration costs, and deducts any lease incentives received. In the simplest case, with none of those extras, the asset equals the liability.
So the liability is the foundation and the asset is the liability adjusted for the costs of getting the lease in place. Once recognised, the asset is depreciated on a straight-line basis, usually over the shorter of the lease term and the asset’s useful life.
A worked example
Take a five-year lease with payments of 10,000 pounds a year in arrears and a discount rate of 5 percent. The present value of those five payments is about 43,295 pounds. With no other costs, the lease liability and the right-of-use asset are both 43,295 pounds at the start.
In year one, interest is 5 percent of 43,295, which is about 2,165 pounds. The 10,000 pound payment therefore reduces the liability by 7,835 pounds, leaving about 35,460 pounds. Depreciation of the asset is 43,295 divided by five, about 8,659 pounds a year. So the first-year charge to profit and loss is roughly 2,165 of interest plus 8,659 of depreciation, about 10,824 pounds, compared with a flat 10,000 pound rent under the old operating-lease approach. That higher early charge is the front-loading effect. The bookkeeping for this example is set out in our guide to IFRS 16 journal entries.
Subsequent measurement
After commencement, the two figures move independently. The lease liability grows by interest and shrinks by payments each period. The right-of-use asset is depreciated over the lease term. They rarely match after year one, and both reach nil by the end of the lease in a simple case.
If the lease changes, for example a rent review or a change in term, the liability is remeasured and the asset is adjusted. Remeasurements are one of the areas where spreadsheets struggle and where dedicated lease accounting software earns its place.
The FRS 102 simplifications
From 2026, FRS 102 uses the same broad right-of-use model but with practical simplifications. Lessees may use an obtainable borrowing rate instead of the harder-to-calculate incremental borrowing rate, and fewer lease modifications require the use of a revised discount rate.
The outcome is very similar to IFRS 16, but the method is a little easier to run, which suits the smaller finance teams that apply FRS 102. The detail is in our FRS 102 2026 guide, and the choice of standard is covered in our comparison of IFRS 16 and FRS 102.