What Is an Asset Audit and Why Does It Matter?
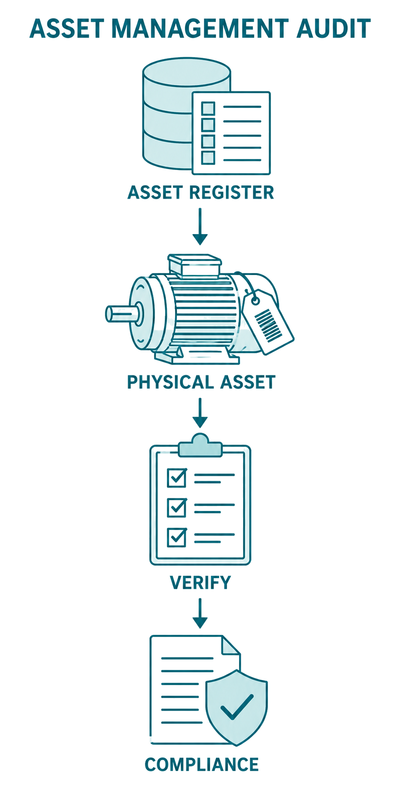
An asset audit provides direct evidence that an organisation’s asset register reflects physical reality. Without periodic verification and routine updates, the register can accumulate ghost assets, misplaced items and other discrepancies. Depending on their value and accounting status, these issues may affect financial reporting, insurance schedules, operational decisions and compliance evidence.
Physical verification normally checks identity, existence, location, status, custodian and tag condition. Cost, depreciation and ownership should be reconciled against appropriate accounting and supporting records. Physical inspection supports existence and location, but it does not by itself establish valuation, ownership or accounting treatment, a distinction reflected in ISA (UK) 500, Audit Evidence. Any discrepancy should be investigated before the register or accounts are changed, and recurring discrepancies may indicate weaknesses in the register maintenance process.
An asset audit is a control, comparable to a stock count in a warehouse. Its purpose is to identify and correct errors before they compound. Treated that way, verification becomes a routine part of maintaining accurate records rather than a crisis response.
Ghost assets can have financial and operational consequences. Depending on their carrying value and how insurance is arranged, they may overstate asset values, distort depreciation or inflate insurance schedules. An audit identifies records that require investigation; confirmed losses or disposals should then be handled through the organisation’s authorised accounting and disposal controls. Our guide to reducing lost and ghost assets covers this in more detail.
How Do You Conduct an Asset Audit? Step by Step
You conduct an asset audit by agreeing the scope, preparing the register, verifying the in-scope assets, recording discrepancies, investigating exceptions and updating records through authorised controls. The audit may cover the full population or a risk-based sample. Barcode or QR scanning can reduce manual cross-checking where suitable tags and mobile tools are available.
- Prepare and scope: define the assets, locations and period to be covered, then export the current register and confirm the available verification method.
- Verify: scan or physically inspect each in-scope asset and match it to the register record.
- Record discrepancies: note assets that are missing, unexpected, in the wrong location, untagged or whose financial details require review.
- Investigate exceptions: trace missing assets, confirm transfers or disposals, identify duplicates and retain supporting evidence.
- Correct and sign off: update records through authorised controls, process confirmed losses or disposals appropriately, and retain the audit evidence and approvals.
The investigation stage is where judgement is needed. A missing asset might have been disposed of without a record, transferred to another site or genuinely lost. Each outcome requires different evidence, approvals and accounting treatment, so the audit is not simply about ticking off what is present. A sound audit ends with every discrepancy investigated and an outcome recorded, not just counted.
What Should an Asset Audit Checklist Include?
A physical asset audit checklist should cover identity, existence, location, tag condition, status and custodian, together with a record of every discrepancy. Where financial reconciliation is in scope, cost, depreciation, ownership and disposal information should be checked separately against appropriate supporting records. A structured checklist makes the audit consistent, repeatable and reviewable.
- Existence: is the recorded asset physically present and identifiable?
- Location: does the physical location match the register?
- Tag condition: is the barcode or QR label intact and scannable?
- Custodian: does the recorded person or department match current responsibility?
- Status and condition: do the recorded status and condition reflect the asset’s current use and physical state?
- Discrepancies and financial follow-up: is each gap logged with a cause, corrective action and any required accounting review?
A consistent checklist is what makes audits comparable over time. When every audit follows the same structure, trends become visible: whether discrepancies are reducing, whether particular sites struggle with accuracy, and whether the maintenance routine between audits is working. Without a standard checklist, each audit is a one-off and little is learned from the last one.
How Does Asset Tracking Make Audits Faster?
Asset tracking can make audits faster by reducing manual cross-checking. Instead of reading a spreadsheet row by row, an auditor can scan each tagged asset and match it to the register, allowing missing, unexpected or misplaced items to be flagged more quickly. The time saved will depend on the number and distribution of assets, tag quality, audit scope and preparation.
Scan-based audits can also create a time-stamped history of checks and changes, supporting evidence of who did what and when where the system records user attribution. For how tagging works, see our guide to barcode asset tracking vs manual tracking.
Faster verification can support more frequent, risk-based spot checks on selected assets. Regular checking can help keep the register current and reduce the number of discrepancies that accumulate before the next wider reconciliation.